Essential Guide to Indian Credit Cards for NRIs
Non-resident Indians routinely rely on local credit instruments for global transactions, yet maintaining an Indian credit card serves vital domestic financial purposes. These specialized cards streamline local rupee expenditures, secure cross-border credit profiles, and establish critical borrowing pathways for future investments back home.
Key Highlights
- Eligible non-residents can now access unsecured Indian credit cards without pledging fixed deposits.
- Maintaining local credit cards prevents domestic credit history from becoming completely dormant.
- Foreign exchange markups between 1.5% and 3.5% can quietly erode overseas spending.
- Failing to convert resident accounts to non-resident accounts risks violating major compliance laws.
Non-resident Indians often depend on credit cards issued in their current countries of residence as primary transaction tools. These financial instruments deliver localized rewards, travel perks, and smooth cross-border functionality.
Nevertheless, an Indian credit card remains highly advantageous for managing expenditures within India, such as settling utility statements, funding family requirements, arranging domestic itineraries, or protecting credit profiles for future loans.
Financial advisors state that Indian credit cards assist non-residents in establishing local credit records, optimizing rupee transactions, and facilitating long-term credit access. Still, applicants must navigate foreign exchange levies, payment structures, statutory compliance under the Foreign Exchange Management Act, and taxation guidelines.
Can NRIs get an Indian credit card without a fixed deposit?
Qualified non-residents can now secure unsecured Indian credit cards from multiple banking institutions without the necessity of locking funds into fixed deposits. BankBazaar Chief Executive Officer Adhil Shetty notes that approvals depend on verified income metrics, existing banking relationships, submitted records, and internal credit profiling.
Concurrently, credit cards secured by fixed deposits remain a highly accessible pathway for numerous applicants. This mechanism particularly benefits individuals who lack active banking relationships in India or cannot provide acceptable documentation of their earnings.
Non-residents who already hold active Non-Resident External or Non-Resident Ordinary accounts should approach their current banking institutions. Leveraging these existing connections can accelerate the mandatory verification processes and simplify overall onboarding protocols.
How an Indian credit card can help maintain your CIBIL score
A widespread misconception exists among non-residents that maintaining an exceptional credit rating in the United States or elsewhere translates directly into seamless loan approvals inside India. Financial systems do not operate across borders in this manner.
Indian financial institutions review domestic credit bureau registries exclusively when evaluating prospective borrowers, according to Zaggle Executive Chairman Raj P. Narayanam.
A CIBIL rating tracks domestic credit activity reported by local financial institutions to Indian credit registries. Narayanam emphasizes that a flawless American credit profile carries no weight when an institution evaluates a home loan application in Mumbai.
This distinction becomes critical for non-residents intending to acquire Indian real estate, obtain equity loans against existing property, capitalize corporate entities, or permanently relocate back to India.
If a non-resident operates an active Indian credit card for minor, consistent expenditures like streaming platforms or utility bills while clearing balances punctually, they construct a viable credit history that proves invaluable during major loan applications, Narayanam observes.
The credit margin separating a low score of 650 from an optimal score of 780 heavily impacts approved interest percentages, overall loan limits, and negotiation leverage with underwriters.
Operating at least one functional Indian credit card represents the most direct strategy for non-residents seeking to prevent their domestic credit profiles from turning dormant.
Charges and features NRIs must check before getting an Indian credit card
Financial specialists counsel applicants to evaluate card attributes far beyond basic marketing incentives.
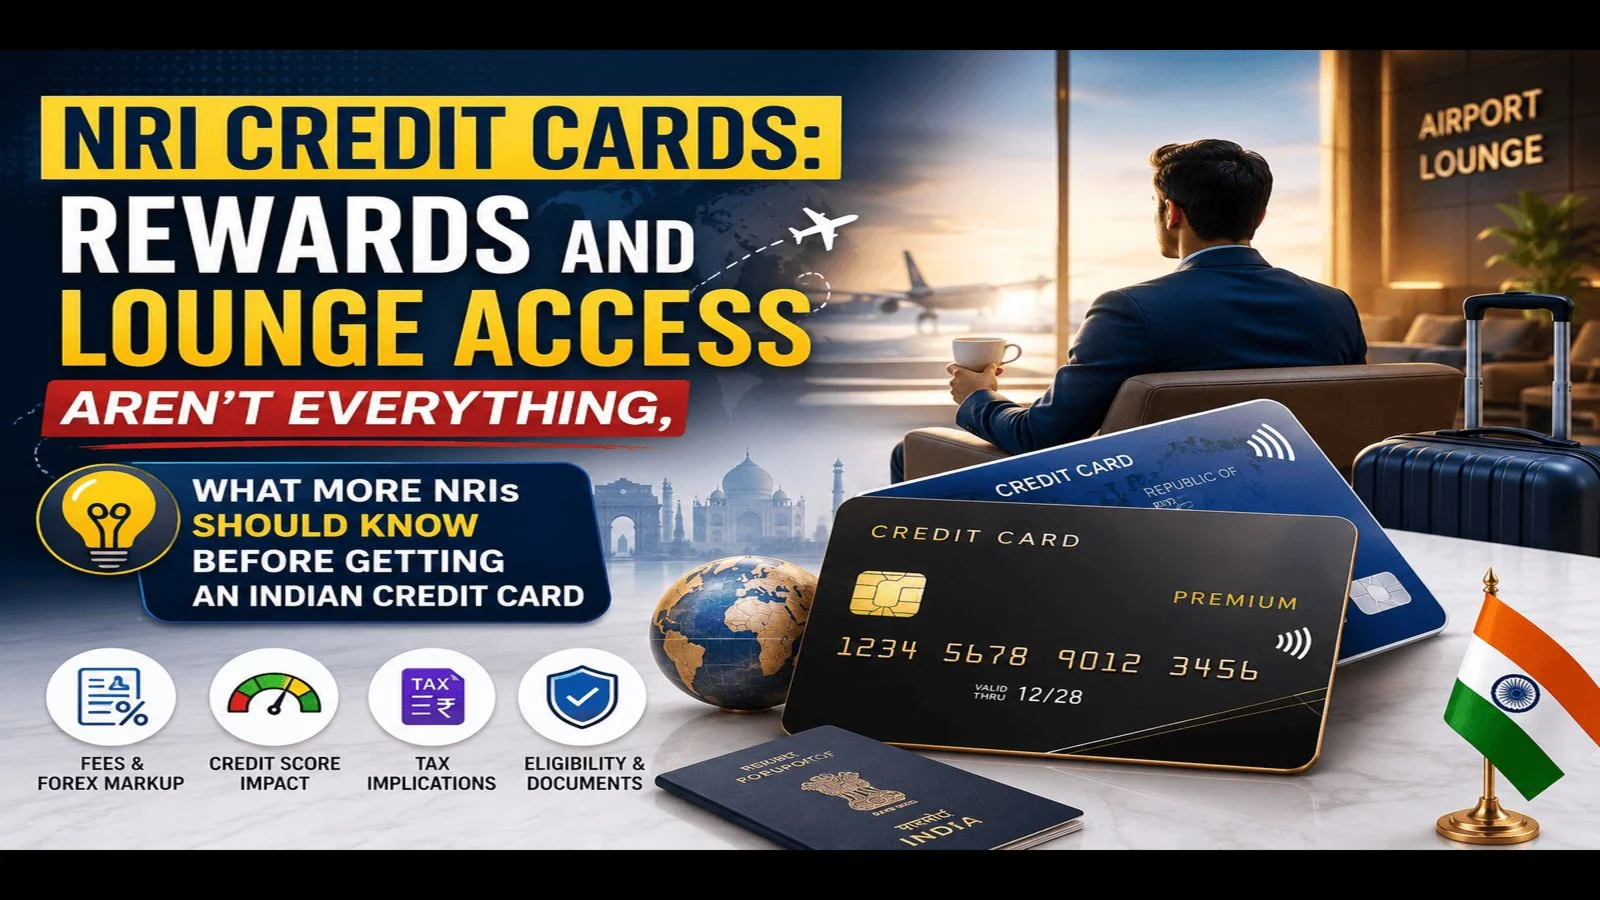
The premier attribute for individuals traveling frequently between international destinations is the foreign currency transaction markup, a feature that Narayanam notes is frequently ignored.
The majority of Indian credit card variants impose fees ranging from 1.5% to 3.5% on international transactions. For individuals charging Rs 10 lakh to Rs 15 lakh annually in foreign jurisdictions, these hidden operational fees systematically deplete substantial capital.
Acquiring a card featuring low or zero foreign exchange markups must serve as an absolute baseline requirement before analyzing secondary perks, Narayanam states.
Once foreign transaction costs are minimized, travelers should assess associated insurance features covering emergency medical circumstances, journey disruptions, and luggage displacement. Complimentary airport lounge access also adds material value for transcontinental flyers.
Dynamic Currency Conversion represents another frequently misunderstood operational feature.
This process triggers when an international point-of-sale terminal offers to process a card transaction in Indian rupees rather than the local currency. Though seemingly convenient, the conversion mechanism applies disadvantageous exchange rates compared to standard network conversions.
When a foreign point-of-sale operator bills an invoice in rupees rather than local tender, the currency conversion matrix becomes less favorable, escalating transaction outlays, Shetty explains.
Market analysts consistently recommend rejecting Dynamic Currency Conversion choices, opting instead to settle all invoices in the native local currency.
International automated teller machine extractions also generate high outlays, given that these transactions trigger immediate cash advance fees and accrue financing charges from the exact calendar day of withdrawal.
Prospective cardholders must also audit annual fee waiver triggers, mandatory spending benchmarks, and reward accumulation expiration timeframes before finalizing a card choice.
Narayanam warns that reward programs require evaluation based on verified redemption purchasing power rather than advertised point accumulation velocities.
The most ignored operational attribute remains the availability of responsive customer support across disparate time zones, Narayanam adds, noting that an individual facing a sudden card freeze at midnight in New York requires immediate resolution rather than standard domestic business hour queues.
How do Indian credit card repayments work for NRIs?
Most banking groups permit non-residents to clear domestic credit card obligations directly via linked Non-Resident External or Non-Resident Ordinary accounts, following standard corporate guidelines. Shetty observes that issuers regularly deploy automated debit choices, lowering the probability of missed deadlines and associated penalty fees.
Nonetheless, non-residents must carefully calculate foreign exchange volatility and cross-border settlement timeframes.
When moving foreign capital home to clear statements, operational processing backlogs and institutional cutoff periods directly dictate when liquid funds clear.
For instance, settling a statement balance of Rs 1 lakh requires varying amounts of foreign currency depending entirely on the spot exchange rate active at the time of conversion, Shetty remarks.
Carrying surplus capital within linked accounts and initiating external transfers days ahead of payment deadlines prevents late payment complications.
FEMA, KYC, and compliance issues NRIs should know
Narayanam highlights that numerous non-residents mistakenly continue utilizing standard resident savings accounts and traditional credit cards long after their residency designation shifts under Foreign Exchange Management Act legal parameters.
When an individual transitions to non-resident status, statutory guidelines require transforming resident checking and savings accounts into specialized Non-Resident External or Non-Resident Ordinary structures, necessitating a parallel update to linked credit instruments.
Maintaining unconverted resident portfolios creates a distinct regulatory compliance mismatch that frequently emerges during mortgage validation steps, revenue audits, or outward capital repatriation, Narayanam cautions.
Consequently, non-residents must formally declare residency adjustments to their banking partners, ensuring account designations and credit profiles are updated to mirror current legal realities.
United States residents must concurrently track foreign reporting mandates, including Foreign Bank and Financial Accounts registries and Foreign Account Tax Compliance Act disclosures where relevant.
For global professionals, operating an Indian credit card has transitioned from a basic convenience for temporary visits into a strategic financial tool.
The instrument preserves domestic credit standing, simplifies domestic family allocations, anchors future borrowing strategies, and links seamlessly with local digital payment infrastructure. Achieving maximum financial utility requires looking past sign-up incentives to closely evaluate transaction markups, clearing timelines, regulatory alignment, and actual reward redemption values.
Future Outlook
As India’s digital payment architecture integrates further with international financial networks, the market for specialized NRI financial products is projected to expand significantly. Financial institutions are expected to introduce more sophisticated, zero-forex credit products tailored specifically for global professionals, removing traditional friction points like fixed-deposit collaterals and cross-border paperwork. Additionally, tighter regulatory integration between the Reserve Bank of India and international compliance frameworks will likely automate residency status updates, minimizing accidental compliance gaps for diaspora members.
FAQs
Can an NRI get an Indian credit card without a fixed deposit?
Yes, eligible non-residents can obtain unsecured Indian credit cards if they satisfy specific banking criteria regarding stable income, documentation, and positive institutional relationships. However, deposit-backed cards remain an alternative for individuals without established domestic credit files.
Why is an Indian credit card necessary for building a CIBIL score?
Indian financial institutions do not evaluate international credit histories when processing domestic loan requests. An individual must generate domestic credit history inside India by consistently using local credit instruments and clearing the balances on time to build a valid CIBIL score.
What is the risk of using a resident credit card after moving abroad?
Continuing to use standard resident accounts and credit cards after becoming a non-resident violates Foreign Exchange Management Act regulations. This compliance failure can disrupt future home loan applications, tax assessments, and the legal repatriation of funds.